Our changing transportation world

By Gary Williams, Director of Transportation and Regulatory Affairs 

The overriding message from the most recent Great Lakes–St. Lawrence Seaway Trade Revitalization Mission was impossible to ignore: Transportation networks are changing quickly in response to bottlenecks, shifting supply-and-demand patterns, geopolitical risk, and geographic advantage. 

Across Africa, Morocco, Portugal and southern Spain, ports and transportation agencies are investing heavily in the infrastructure needed to capture emerging trade. The common theme is clear: Ports are not waiting for demand to arrive. They are building capacity, improving rail connections, deepening channels, expanding terminals and positioning themselves for a very different global trade map. 

Africa’s long-term demand potential 

One of the most consequential changes in global trade is Africa’s population trajectory. A July 2024 projection from the United Nations Population Division anticipates that Africa’s population could increase by roughly 1 billion people, from approximately 1.5 billion today to 2.5 billion by 2050, representing about 28% of the world’s population. 

For U.S. agricultural exporters, this points to a substantial long-term expansion in demand for food, feed, livestock, poultry, aquaculture, edible oils, protein and food-processing inputs. A larger and increasingly urban population will require more reliable supplies of grains, soybeans, soybean meal, vegetable oils, specialty food ingredients and animal-protein inputs. 

Of course, this opportunity is not automatic. Future import demand will depend on income growth, agricultural productivity, trade policy, port and inland infrastructure, foreign-exchange availability and the competitiveness of U.S. suppliers relative to Brazil, Argentina, Black Sea suppliers, Europe and Asia. 

Still, the projected addition of nearly 1 billion people makes Africa one of the world’s most important long-term demand-growth regions for agricultural trade. The transportation world is taking note. 

Morocco’s growing gateway role 

Morocco is rapidly positioning itself as a logistics gateway between Europe, Africa and the Americas. 

Tanger Med began operations only in 2007–2008 and expanded with Tanger Med 2 in 2019. In December 2024, APM Terminals completed an additional 2 million-TEU expansion. Looking ahead, Morocco has announced approximately $2.8 billion in investment for 2026–2030, intended to increase Tanger Med’s capacity from 11.1 million TEU handled in 2025 to 15 million containers by 2030. 

Tanger Med is fundamentally a transshipment port. Cargo is not intended to sit long; speed, connectivity and vessel transfers are the business model. More than 75% of its activity is targeted toward transshipment, and it is now by far the largest container port in Africa. 

The port’s geographic position has become even more valuable amid conflict and uncertainty around the Suez Canal and Red Sea shipping routes. For carriers seeking an efficient western Mediterranean and Atlantic transshipment option outside the immediate conflict zone, Tanger Med is increasingly attractive. 

Morocco is also developing the new Dakhla Atlantic Port near El Argoub, roughly 70 kilometers north of Dakhla city, in territory administered by Morocco in Western Sahara. Construction has advanced significantly, with project reporting in mid-2026 indicating that the overall project was approximately 62% complete and the marine access bridge about 85% complete. Moroccan officials have targeted commissioning in 2028. 

With a planned draft of 23 meters, Dakhla Atlantic is designed to accommodate the world’s largest vessels. The port is also being positioned as a future gateway for the Sahel and nearby landlocked African countries, supported by regional cooperation and planned road, logistics, industrial and trade connections. 
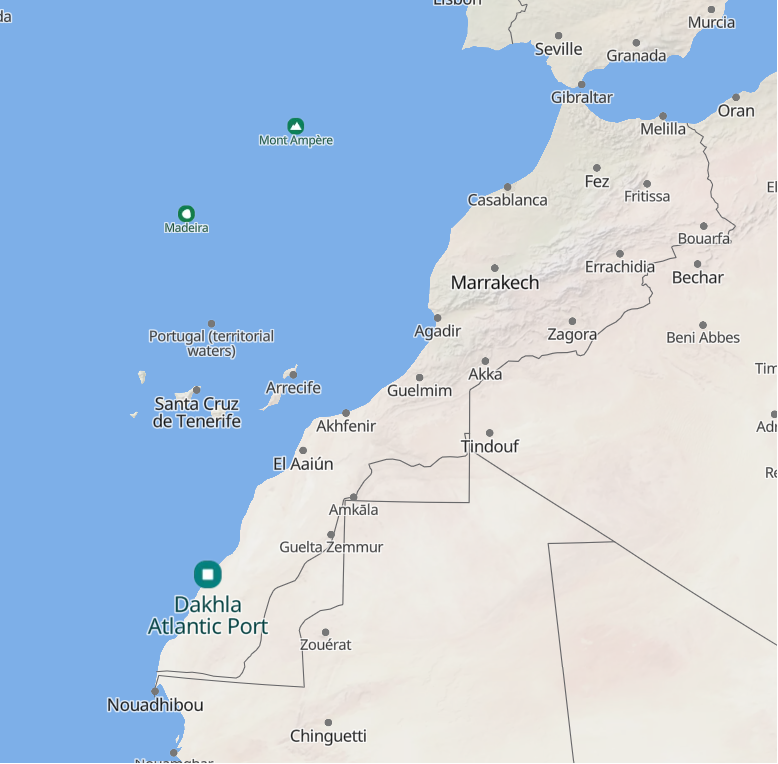
Map image by MapCarta.

Expanded opportunities in Portugal 

The next stops on the trade mission included Lisbon, Aveiro, Porto and Leixões, Portugal. Here again, the delegation found substantial port capacity and major planned investments aimed at serving not only Portugal, but also Spain and inland European markets connected by rail. 

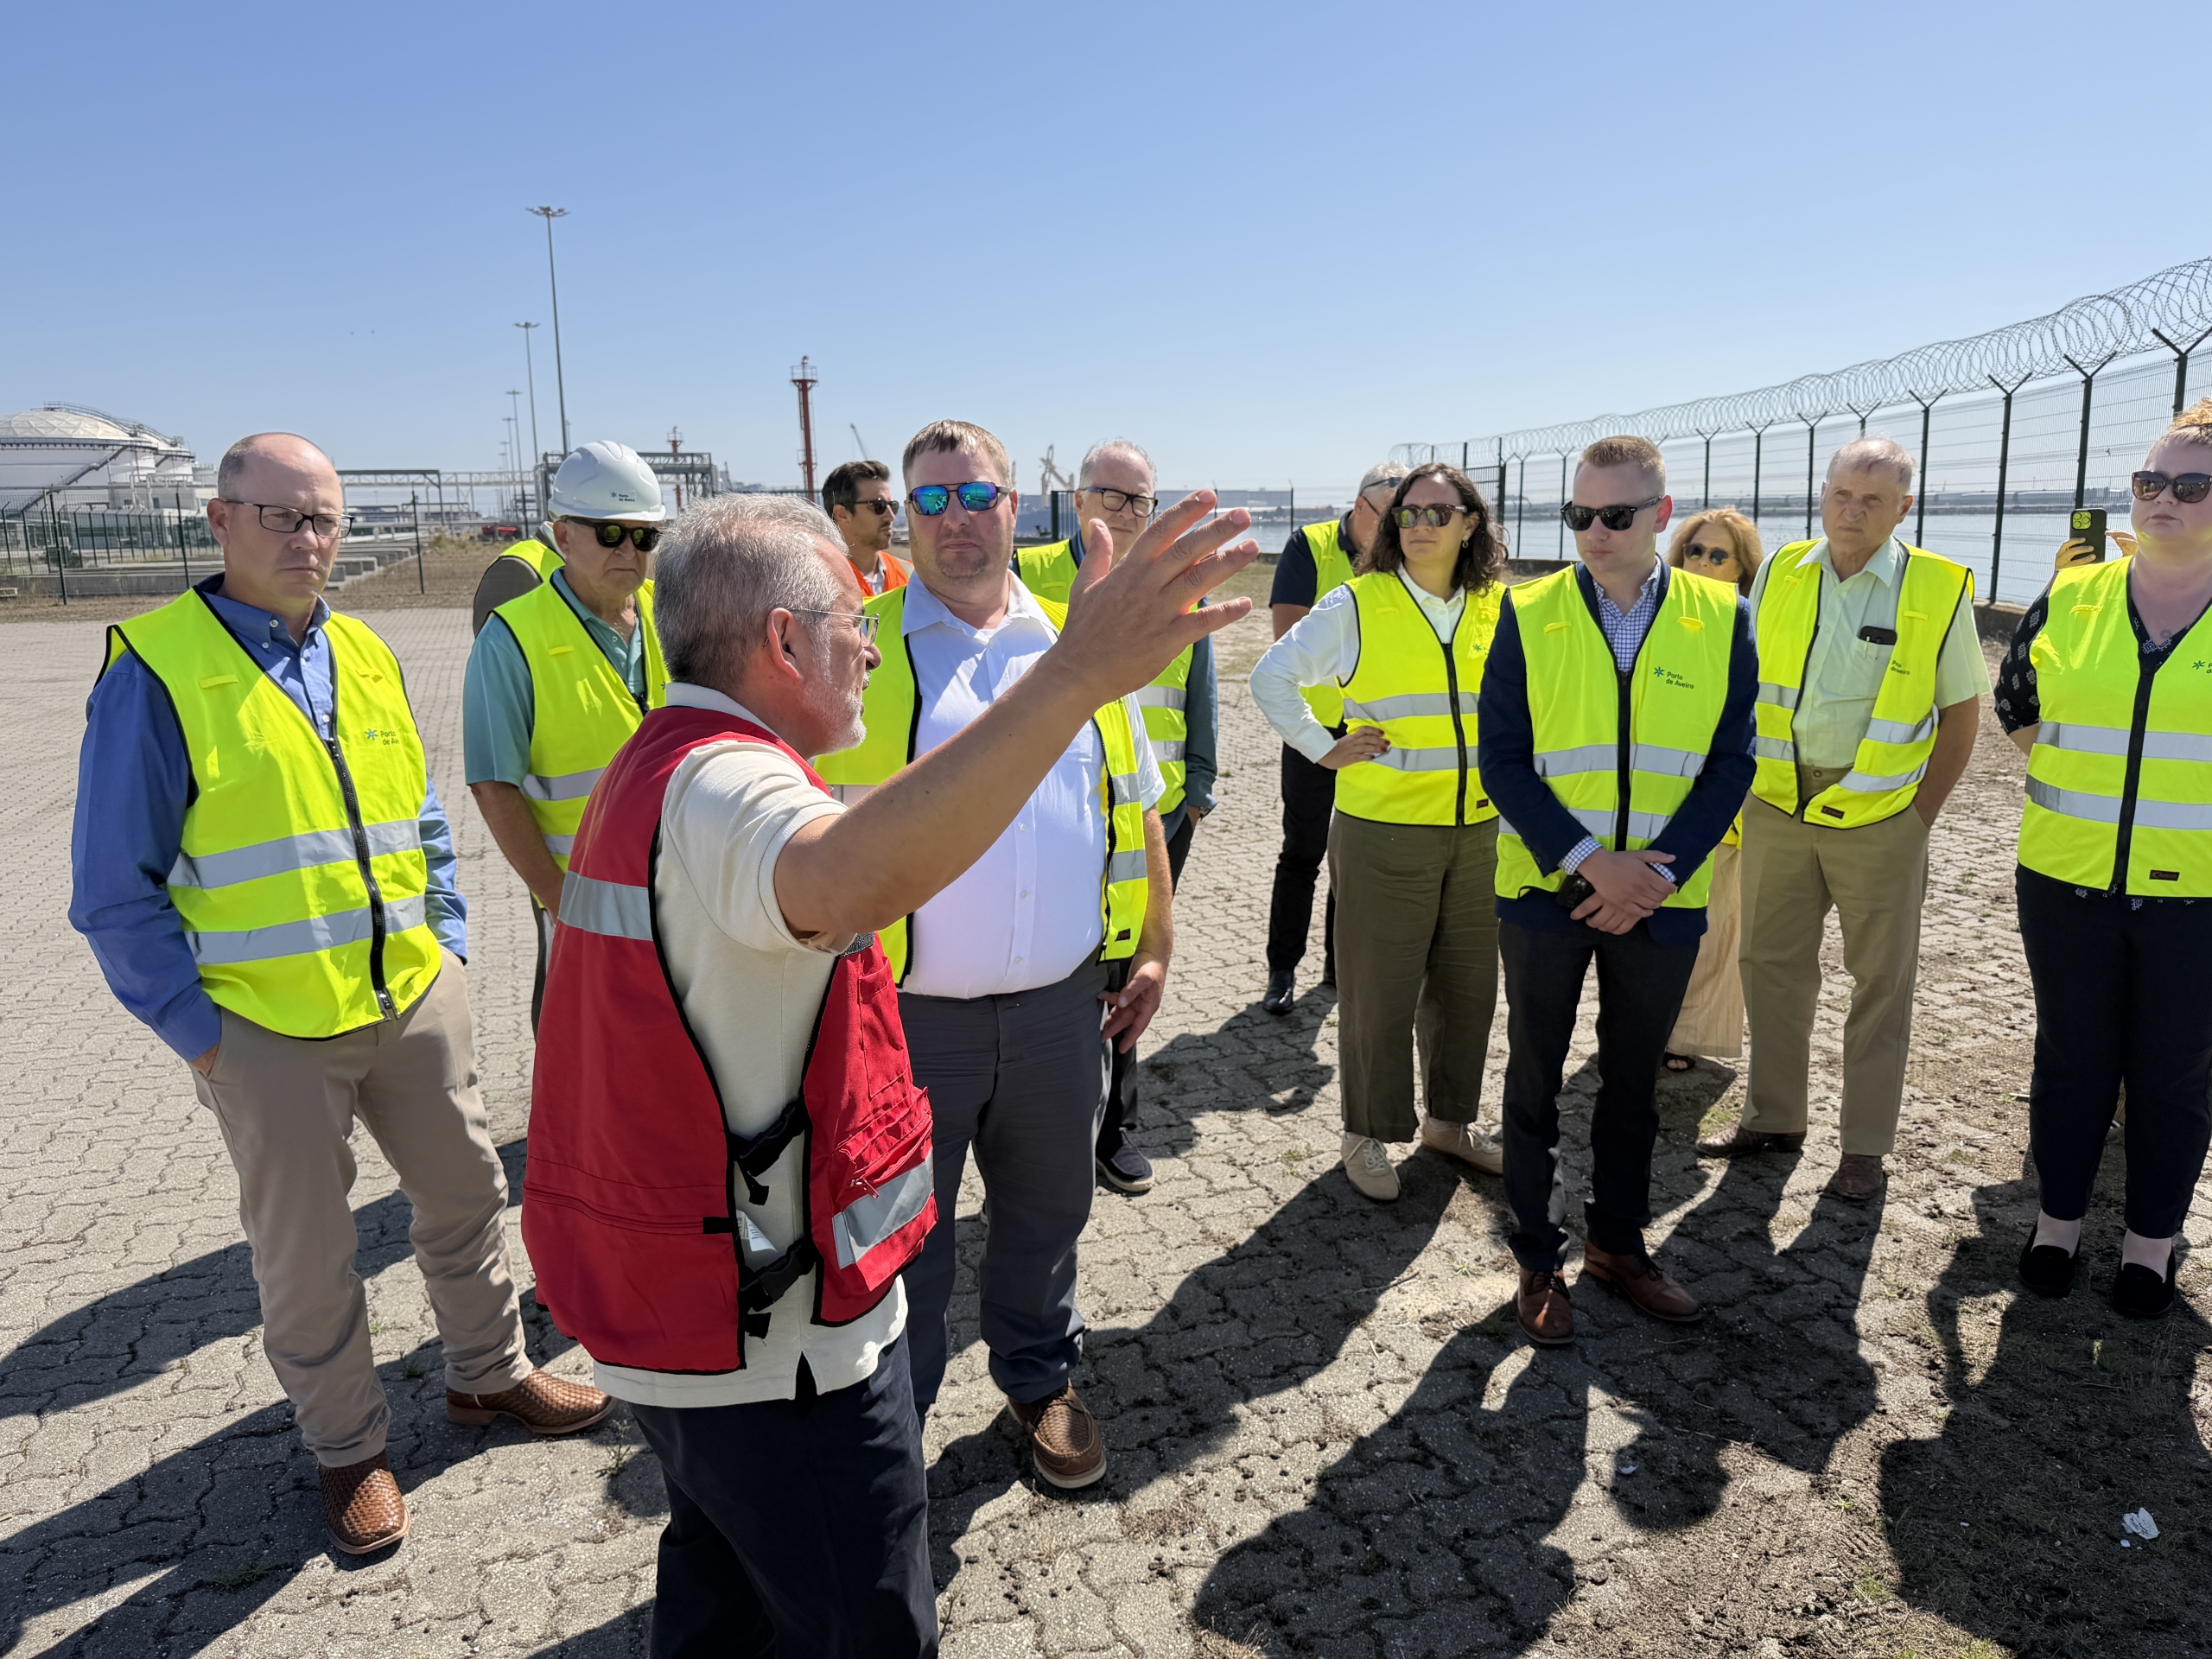
At Aveiro, local officials highlighted Portugal’s new Porto–Lisbon high-speed passenger rail project, supported by the European Investment Bank. The estimated €3 billion project will build a new high-speed line between Porto and Lisbon, reducing the current roughly three-hour passenger trip to approximately one hour and 15 minutes. 

The passenger-rail project also has freight implications. By shifting passenger trains to a new dedicated line, it can help free capacity on the conventional rail network for freight movements serving Spain and interior European markets. That additional rail capacity could strengthen Aveiro’s role as an initial discharge location for cargo headed into Iberia and beyond. 

Aveiro is planning approximately €116.9 million in investment through 2030 for larger-vessel access, rail-connected logistics and industrial expansion, and port modernization. Its strategy includes improved navigability, a maritime-road-rail intermodal terminal at the port’s logistics and industrial zone, digital operating systems, shore power and energy-transition infrastructure. 

Leixões, near Porto, is pursuing an equally significant modernization and expansion program. Its long-range plan includes €931 million in investment through 2035, including approximately €430 million for an expanded container terminal. The port’s objective is to increase annual cargo volumes from about 14.4 million tons to 20 million tons, while container throughput is targeted to reach 1 million TEU. 

For both Aveiro and Leixões, the message is consistent: greater rail integration, deeper maritime access, modern terminals, and industrial logistics capacity are essential if Portugal is to capture more cargo moving between the Atlantic, Spain and the wider European Union. 

Southern Spain’s strategic advantage 

As the team divided into a smaller group to assess southern Spain as a possible future trade-mission destination, we were again struck by the scale of investment and growth planning at Algeciras and Málaga. 

Both ports emphasize speed, efficiency and their geographic advantage at the entrance to the Mediterranean. They are positioning themselves as alternatives for cargo that may otherwise move through the congested northern European gateways of Rotterdam, Amsterdam and Antwerp. 

Algeciras is already one of Europe’s leading container and transshipment ports, handling more than 100 million metric tons in 2025. The port has established a goal of approximately 120 million tons by 2030, supported by major public and private capital investments. 

Near-term investment is projected at approximately €1.388 billion, combining public and private infrastructure spending and terminal investments. The program includes expanded container terminal capacity, improved rail access, port-road connections, new roll-on/roll-off and ferry infrastructure, shore power and broader modernization of port systems. 

After the planned terminal investments, Algeciras expects container capacity to exceed 7.5 million TEU annually, with infrastructure reserved for as much as 9 million TEU by 2035. Its strategy is not only to protect its role as a major transshipment hub, but also to capture more import-export cargo moving between Iberia, Europe, Africa and the Americas. 

Once again, geography matters. The Strait of Gibraltar remains one of the world’s most strategically important maritime locations, and Algeciras is using investments in terminals, rail, energy and landside logistics to convert that geographic advantage into sustained commercial growth. 

A transportation system in motion 

The takeaway from this United State Identity Preserved Alliance-led mission is that global transportation patterns are not static. Ports, railroads, logistics providers, shippers, and governments are responding to changing population centers, supply-chain disruptions, congestion, geopolitical risk, environmental requirements and competitive pressures. 

Africa’s population growth is creating future demand. Morocco is expanding its role as a gateway between continents. Portugal is linking port development to new rail capacity and Iberian market access. Southern Spain is building on strategic geography to become an increasingly important alternative gateway for European cargo. 

Over the next five years and well into the next quarter century, transportation routes are likely to continue shifting as end-use markets evolve and new efficiencies emerge. Shippers should recognize that transportation plans will be influenced by this changing world: a world where infrastructure investment often anticipates trade growth rather than merely reacts to it.
USIP Alliance trade mission strengthens seaway export opportunities

The U.S. Identity Preserved Alliance led agricultural and transportation representatives on a trade mission to Morocco and Portugal to explore how increased two-way trade could strengthen the Great Lakes-St. Lawrence Seaway as an export route for identity preserved crops and other value-added agricultural products. 
 
In Morocco, the delegation toured port facilities in Casablanca and Tangier and held a seminar with Moroccan port representatives. Discussions focused on bringing additional imports and shipping containers into inland Great Lakes ports, creating more reliable opportunities to move agricultural products back through the Seaway to international customers.  
 
Delegates also learned about Casablanca’s expansion plans and Tanger Med’s position as Africa’s largest container port and an important gateway to markets across Africa, the Mediterranean and the Middle East. 
 
In Portugal, the delegation visited ports in Lisbon, Aveiro and Leixões and also delivered its seminar. Speakers and participants included representatives from the Alliance; the Great Lakes St. Lawrence Seaway Development Corporation; Minnesota and Wisconsin departments of agriculture; farmer-leaders from soybean organizations in Minnesota, Wisconsin and Ohio; and the Ports of Indiana.   
 
Overall, the mission reinforced the Alliance’s strategy of pairing international market development with practical transportation solutions. By building relationships with overseas ports and demonstrating the Seaway’s direct connection to the U.S. agricultural heartland, the Alliance aims to generate more balanced cargo flows, improve container availability and establish new export channels for U.S. value-added agriculture. 
 
The trade mission was made possible with funding from the Minnesota Soybean Research & Promotion Council, Wisconsin Soybean Marketing Board, Ohio Soybean Council and Illinois Soybean Association. 
 
Following the mission, USIP Alliance staff went on to Spain for visits to ports at Huelva, Cadiz, Algeciras and Malaga in preparation for 2027’s trade mission. 

Spotlight: Morocco

The U.S. Identity Preserved Alliance’s St. Lawrence Seaway Trade Revitalization Program’s 2026 trade mission began this week in Morocco with visits to ports in Casablanca and Tangier.  

Morocco continues to be a growing market for U.S. agriculture and is an important geographic location as a global passage and key crossroad to the Mediterranean and Middle East, as well as to the rest of Africa. More than 100,000 commercial ships per year – 300 per day – pass through the Strait of Gibraltar, the narrows between Morocco and Spain along which Tangier’s Tanger Med port sits. 

U.S. Identity Preserved Alliance held a seminar for port representatives in Casablanca, speaking about opportunities and challenges for two-way trade between Moroccan ports and U.S. inland ports along the Great Lakes and St. Lawrence River. Speakers included Gary Williams, USIP Alliance director of transportation and regulatory affairs; Jazmine Jurkiewicz, St. Lawrence Seaway Development Corporation international trade specialist; Minnesota soybean farmers Paul Freeman and Ron Obermoller; Emily Jerve, Minnesota Department of Agriculture domestic marketing supervisor; and Jacob Leum, Wisconsin Department of Agriculture, Trade and Consumer protection international trade representative. 

Two-way trade is important to the north-central states, as the imports of products into the St. Lawrence Seaway bring vital equipment, such as containers, to inland ports that could take value-added agricultural exports back out. 

Since opening in 2017, Tanger Med has become the largest container port in Africa and 17th largest in the world. The port’s terminals operate well above original capacity design, meaning continued expansion of the container market in Morocco is strong. This coincides with burgeoning container capabilities on the Great Lakes, including upcoming opportunities in Burns Harbor, Ind., Monroe, Mich., and recently renewed capacity at Duluth-Superior (Minn., Wis.). 

At Casablanca, officials from the National Ports Agency discussed expansion of Casablanca and other ports in Morocco, noting plans to deepen ports to accommodate Panamax and post-Panamax vessels. While the port moved 32 million metric tons of cargo in 2025, there is capacity to handle 50 million metric tons, along with future expansion.  

Other Moroccan ports, including deep-water port project in Dakhla, provide more opportunities to satisfy consumer demand and the growing population throughout Africa, with dry-port movement to landlocked countries Mali, Chad, Niger and Burkina Faso. 

The delegation was impressed with the connectivity among Moroccan ports, particularly after seeing firsthand the benefits of its geographic location. And one seminar participant explained that Morocco’s crossing point benefits new repair and distribution opportunities, allowing for reuse of products to meet consumer demand elsewhere on the African continent.  

Following the Moroccan leg of the trade mission, the delegation moved on to Portugal for port visits and seminars in Lisbon and Porto. Other seminar speakers for those events include Wisconsin soybean farmers Jonathan Gibbs and Matt Wagenson, Ohio farmer Adele Flynn, and Christina Connelly, Minnesota Department of Agriculture international trade supervisor. 

USIP Alliance’s St. Lawrence Seaway Trade Revitalization Program is supported with funding from Wisconsin Soybean Marketing Board, Minnesota Soybean Research & Promotion Council, Ohio Soybean Council and Illinois Soybean Association. 

The Northwest Seaport Alliance exploring operational changes to better serve customers

The Northwest Seaport Alliance (NWSA) is evaluating how the Seattle–Tacoma gateway can better serve customers and compete more effectively on the West Coast. The effort is focused on reclaiming market share by delivering the consistent, reliable service customers expect.

Any potential changes to NWSA’s operating model remain exploratory at this stage. As part of that process, the gateway is assessing how it can achieve better results for customers and the broader region.

“We are considering a range of options, to be developed in partnership with our supply chain stakeholders,” said John Wolfe, CEO of The Northwest Seaport Alliance. “Those considerations include everything from a more prominent role for NWSA in gateway operations to gateway‑wide performance metrics negotiated in good faith with our marine terminal operators.”

Wolfe emphasized that any path forward would be developed collaboratively with supply chain stakeholders.

Consistency and speed to market are key drivers in these discussions. Customers have told NWSA they need predictability and faster cargo movement, and those are the improvements the NWSA is working toward regardless of the operational model it ultimately pursues. NWSA remains committed to best-in-class service and to making the gateway more responsive to market changes while delivering more uniform service across Seattle and Tacoma.

“Representing value‑added shippers who depend on efficiency and available capacity at NWSA, the USIP Alliance is encouraged by their direct involvement in identifying and implementing measures to improve fluidity and support increased cargo volumes,” said Gary Williams, director of transportation and regulatory affairs for USIP Alliance. “This approach also allows NWSA to gain firsthand insight into the effectiveness of operational practices they have long encouraged terminal operators to adopt. There is clear value for all stakeholders in NWSA taking an active role in terminal operations, and it reinforces their commitment to growth and enabling greater throughput at the port.”

USIP Alliance joins the conversation at AgTC Annual Meeting

Several U.S. Identity Preserved Alliance members and staff attended the Agriculture Transportation Coalition (AgTC) Annual Meeting last week in Tacoma, joining other agriculture transportation professionals for networking and education. 

Competitive Shipping Action Team Chair Jennifer Schneider and Gary Williams, director of transportation and regulatory affairs, participated in a panel focused on the growing challenges agricultural exporters face from increasingly unstable vessel sailings, booking reliability and shifting Earliest Return Dates (ERDs). These disruptions often occur without notice and continue to drive significant cost increases and operational uncertainty across the supply chain. 

Schneider provided a series of real-world examples illustrating how these inconsistencies directly impact exporters, including lost sales opportunities, reduced margins and ongoing difficulty in planning shipments. Her remarks underscored the compounding effect of unreliable service on agricultural commodities that depend on predictable logistics to remain competitive in global markets. 

Williams complemented these insights by outlining recent advocacy efforts, including a letter submitted by the Alliance to members of the Senate Commerce Committee. The letter calls for greater attention to these issues within the context of the Federal Maritime Commission (FMC) reauthorization, urging policymakers to support enhanced data collection, transparency and regulatory guidance aimed at identifying and addressing problematic practices across the supply chain. 

Broader market conditions were also a central theme of the discussion. Kuehne + Nagel presented for those gathered a cautious outlook for the national economy, while the Journal of Commerce offered a more tempered view, suggesting that recessionary pressures, particularly those tied to fuel costs, may not materialize as strongly as anticipated. Despite differing perspectives, speakers generally agreed that ongoing geopolitical factors, including rerouted vessels avoiding the Red Sea and congestion near the Strait of Hormuz, are extending transit times and tying up capacity, thereby supporting elevated base freight rates in a time when the container capacity should now be far overbuilt. 

As rate structures continue to evolve, other panelists/speakers noted a clear distinction between fuel surcharges and base rates. Carriers have consistently demonstrated the ability to pass fuel-related costs through surcharges, while base rates remain largely insulated. At the same time, reiterating insights shared from the Northwest Seaport Alliance’s Peak Planning session highlighted how carriers are managing capacity, both through some delayed container production and increased container utilization, to prevent rates from falling sharply through the inefficiencies created in the ocean freight network. 

This dynamic creates a delicate balance for exporters. While lower rates may appear beneficial, excessively depressed pricing can reduce incentives for carriers to prioritize export cargo or maintain service on less profitable routes. Conversely, high import-driven rate environments can encourage rapid repositioning of empty containers, further disadvantaging exporters. Panelists emphasized that a sustainable “middle ground” is needed – where rates support balanced trade flows without distorting service priorities. 

Looking ahead, labor negotiations were also identified as a key variable. With the International Longshore and Warehouse Union contract set to expire in 2028, comparisons were drawn to the recent International Longshoremen’s Association agreement on the East Coast, which included a substantial 62% wage increase and limits on automation. Questions remain as to how West Coast labor negotiations will factor in global competitiveness, particularly from the perspective of U.S. exporters. 

Finally, several participants highlighted emerging tools and data capabilities that track on-time performance, sailing reliability and other key metrics. These tools are increasingly being used to help both carriers and shippers better understand patterns, improve decision-making and adapt to ongoing volatility in the supply chain. 

Thoughts and what I heard from Northwest Seaport Alliance Peak Planning Meeting

By Gary Williams, Director of Transportation and Regulatory Affairs

I’ve compiled some thoughts after listening to analysts from the Journal of Commerce and other industry stakeholders at the Northwest Seaport Alliance Peak Planning Meeting. Market signals show a less optimistic scenario for exporters ahead of export peak season. S&P recently revised its global growth projection downward from 2.6% to 2.1%, signaling a more cautious outlook for trade demand in the months ahead. While upcoming May and June data may not immediately reflect this slowdown due to comparison with a period that was weak the previous year, so appears more optimistic than it perhaps should.

Trade flows are shifting in notable ways. Chinese exports to the U.S. have declined by approximately 5%, yet this contraction is offset by remarkably strong export volumes to the rest of the world. Some Chinese ports are operating at nearly 90% capacity utilization. This divergence is widening the Chinese export/import imbalance and reshaping global trade lanes. At the same time, container spot rates have increased significantly over the past four weeks, rising 9-11% year-over-year, indicating tightening conditions despite broader economic concerns.

Fuel costs are emerging as a major pressure point. Bunker prices have doubled, and the financial impact is expected to intensify in July when bunker adjustment factors (BAFs) are formally updated. In the interim, carriers are implementing emergency surcharges to bridge the gap. Compounding this, additional compliance costs tied to fuel regulations, particularly ensuring vessels are operating with appropriate low-sulfur fuels, are adding to operational expenses that will ultimately be passed along to shippers.

Carriers are also taking more discipline in capacity management, driven by financials. Service suspensions and an increase in blank sailings are expected as lines shift vessel allocations away from underperforming routes. Despite continued overcapacity in the market, carriers are less willing to operate at a loss, supported by stronger balance sheets following the highly profitable pandemic-era years. Industry consolidation has further reinforced this discipline, with roughly 10 major carriers now dominating the market compared to about 20 in the past.

Looking ahead, capacity dynamics remain complex. Approximately 35% of the current global fleet is scheduled to come online within the next two years. However, much of this newbuild capacity consists of smaller vessels intended to replace aging ships and serve regional and secondary port markets, rather than dramatically expanding overall capacity. Meanwhile, scrapping rates have not accelerated as expected, in part due to ongoing equipment constraints.

Port congestion is also re-emerging as a concern in key regions. Congestion at some ports meanwhile, continues to add pressure to an already strained system. On the inland side, rising diesel costs are pushing drayage rates higher, while tighter trucking capacity, driven in part by a reduction in foreign CDL drivers, is nudging trucking rates upward. This is contributing to a modest shift toward rail, where feasible.

Although liquefied natural gas (LNG)-powered vessels are somewhat insulated from fuel price volatility, the majority of the global fleet continues to rely on low-sulfur diesel with scrubber systems to meet emissions requirements, leaving most operators exposed to rising fuel costs.

As the industry approaches peak season, the outlook is defined by a combination of cautious demand expectations, disciplined capacity management based on financial impacts, and escalating supply chain operating costs being passed along. The result is a market environment where volatility is likely to persist, and stakeholders across the supply chain will need to remain agile in response to significantly evolving conditions.

Container shipping sector likely will see some significant changes and increased complexities in getting equipment, stability in bookings/sailings/ERDs and rate impacts.

Transportation Go! unveils star-studded agenda in Chicago

The speaker lineup for Transportation Go! April 8-9 at the InterContinental Hotel Magnificent Mile in Chicago is bound to turn heads. With a stacked roster, including Mike McCoshen, Administrator of the Great Lakes St. Lawrence Seaway Development Corporation and FMC Commissioner Max Vekich, and a newly expanded agenda, the conference will make value-added supply chain waves through vibrant discussions that will stop attendees in their tracks.

Other confirmed speakers include:

  • Gene Seroka, Port of Los Angeles
  • Patrick Fuchs, Surface Transportation Board
  • Sten Konst, Spliethoff Group
  • Dwight Robinson, LA Grain
  • Anthony Fisher, U.S. Maritime Administration
  • John Wolfe, Northwest Seaport Alliance
  • Jonathan Gold, National Retail Federation
  • Andy Bradfield, Iowa Interstate Rail
  • Jody Peacock, Ports of Indiana
  • Mark Wegner, Twin Cities & Western Railroad
  • Brent Bois, Calhoun Truck Lines
  • Max Fisher, National Grain and Feed Association
  • Carlos Pozuelo, Barnes and Thornburg
  • Ken Carey, St. Lawrence Seaway Management Corporation
  • Ted Prince, Tri-Cities Transload
  • Richard Hyde, British Consul General
  • Peter Hirthe, Great Lakes St. Lawrence Seaway Development Corporation
  • Brian Oszakiewski, American Great Lakes Ports Association
  • Libby Ogard, Prime Focus LLC

New to the agenda in 2026 is a boat reception on Chicago’s First Lady, sponsored by the Illinois Soybean Association (ISA). Sponsors also include the Illinois Department of Agriculture, South Dakota Soybean Research and Promotion Council, Wisconsin Soybean Marketing Board, Minnesota Soybean Research & Promotion Council, Ports of Indiana, North Dakota Soybean Council, Calhoun Truck Lines, Kaleris, Indiana Soybean Alliance, Profinium, Tri-Cites Intermodal, Friederichs Seed, Scoular, Port Milwaukee, Northwest Seaport Alliance and Duluth Cargo Connect.

In addition to the conference, event host U.S. Identity Preserved Alliance will hold their annual meeting at the same location on April 7, during which board of director elections will take place, and the annual Alliance Honors will be presented. Register for both events at transportationgo.com.

Updates from TPM26

By Gary Williams, Director of Transportation and Regulatory Affairs 

United States Identity Preserved Alliance (USIP Alliance) Director of Transportation and Regulatory Affairs Gary Williams was in California last week with the conflict in the Middle East having erupted only scant days before the start of TPM26, the largest global container shipping and supply chain conference, in Long Beach, Calif.

With turbulent global affairs affecting every aspect of the supply chain, there wasn’t a shortage of topics to explore, and robust discussions were the center point of the conference. The Strait of Hormuz was a central focus owing to the turmoil in the Middle East. During the first day of programming, ONE’s Jeremy Nixon remarked that the container line has 750 vessels tied up in the Strait of Hormuz. The region can only refine and store oil for roughly 21-25 days without access through the Strait of Hormuz before refining has to cease or dramatically decrease, causing an expected price surge for a barrel of oil. As of now, the market is already anticipating a bunker fuel price increase, which will be felt by consumers and shippers worldwide.

Another constant theme seems to be that the unpredictability related to global trade policy and geopolitical policy has become a backdrop of noise. Companies are learning to not react with sudden announcements and subsequent changes. Additionally, a drawn-out war in the Middle East will likely have winners and losers, but those outcomes can’t be fully known either. In this landscape, shippers seem fixed upon focusing capitalization investments on advanced systems for monitoring, analyzing and providing solutions for how to route, warehouse and inventory container cargo, rather than operational investments based on predictable near-term forward business. Also discussed on the second day, was the uneasiness felt regarding U.S. tariffs. While some carriers have seen a shift in trade lanes as different “dance partners” pick up slack created by tariffs, most stakeholders have adapted the mindset not to panic because whatever is in the air today is likely to change tomorrow. The scope of planning is for a more distant day in the future, more in the order of 8-10 years, when the U.S. has repositioned trade agreements, and a new normal takes place.

Throughout the conference, we heard that different supply chain participants on the export side struggle with solving the continual changes of earliest return dates and how to shift it to a “reasonable” and more stable environment. In conversations led by USIP Alliance, we’ve had a good amount of support on our (and others) push for the issue to be addressed.

Lars Jensen, CEO and partner of Sea Intelligence Consulting, wrapped up the 25th annual TPM conference. Jensen predicted consolidation among Asian carriers, gave his thought that Alliances stand a good chance of changing in the next few years, with MSC and CMA remaining on their own, and a further possibility that the canal America once considered to build across Nicaragua may still happen, but this time spearheaded by China.

All of these same themes and issues – and more – will be discussed at Transportation Go! April 8-9 in Chicago.

Seaway synergy: Highway H2O unlocks Great Lakes potential

Competitive shipping relies upon resiliency, reliability and redundancy. Coupled with the opportunities that geopolitics, European Union and United Kingdom policies and shifts in trade partnerships bring, the Great Lakes hold potential opportunities not seen in the past decades.

The 20th annual Highway H2O Conference drew a crowd to Toronto for three days of discussion about these topics and the future of the bi-national St. Lawrence Seaway. The Seaway’s unique shared governance between Canada and the United States framed the event, reminding attendees that decisions on one side of the border ripple across all the Great Lakes.​ SSGA Director of Transportation & Regulatory Affairs Gary Williams attended and spoke at the event, hosted jointly by the St. Lawrence Seaway Management Corporation (SLSMC) and the U.S. Great Lakes St. Lawrence Seaway Development Corporation (GLS).

The attendees reflected the system’s complexity and potential. They included leaders of the two operating entities of the Seaway, including Administrator Mike McCoshen from the GLS and SLSMC President Jim Athanasiou, alongside shippers, freight brokers and forwarders, port and terminal leaders, regulatory and governmental agencies, and other Lakes/Seaway stakeholders. Their conversations carried a common thread: capacity exists on the system today, but realizing its competitive edge will take coordination, investment and a new way of thinking about freight.​

Williams presented about SSGA’s trade revitalization program designed to educate importers and exporters on the advantages of the Seaway and to actively address barriers that keep volumes below the corridor’s true capacity.​ The program is supported by the Ohio Soybean Council, Minnesota Soybean Research & Promotion Council, Wisconsin Soybean Marketing Board and Illinois Soybean Association.

At the heart of Williams’ story was the idea that the Seaway is not just an alternative route, but a strategic piece of a diversified transportation portfolio. He outlined how the corridor can complement rail, truck and coastal ocean routes, offering resilience, cost-competitiveness and environmental benefits that appeal to cargo owners looking for redundancy and lower emissions. Yet, he was direct about the challenge: lower current trade volumes can make it harder to build frequent services and justify new infrastructure, even though the physical capacity is already in place.​

Containerization entered the discussion as both a challenge and an aspiration. While some attendees talked about the long-term goal of establishing a dedicated feeder system on the Lakes, Williams urged the group not to wait for a perfect future model. Instead, he encouraged them to build the container market incrementally, leveraging the flexibility of many vessels already entering and leaving the Seaway that can carry containers alongside other cargoes.​

Williams invited stakeholders from across the value chain to join the trade revitalization program and deepen their understanding of the corridor’s potential. He pointed to the upcoming Transportation Go! conference April 8-9, 2026, in Chicago as a next touchpoint, encouraging participants to continue the conversation there and help shape solutions that turn today’s ideas into tomorrow’s sailings.

MARAD, FMC nominees call for bold action

Compiled by Gary Williams, Director of Transportation & Regulatory Affairs  

President Donald Trump’s newly nominated Maritime Administration (MARAD) chair, Stephen Carmel, appeared before the Senate Commerce Committee on Oct. 22 to pledge an aggressive focus on supply chain safety, connectivity and enhancing efficiency across America’s freight corridors.  

Carmel, bringing decades of leadership experience from roles as president of U.S. Marine Management and executive at Maersk Line Limited, opened his testimony with a message of strategic urgency: 

“A strong maritime sector is not nostalgia – it’s strategy. It means resilient supply chains we control; credible logistics for our joint forces; good jobs across our coasts, rivers and Great Lakes; and the freedom to move what America needs, when and where America needs it – under our own flag. We will not be the generation that stood on the sidelines and passively watched our noble industry die. We will be the generation that rebuilt it – stronger, smarter, faster and ready.” 

Carmel, a graduate of the U.S. Merchant Marine Academy with hands-on sea experience, is seen by congressional supporters as a policy expert and operations leader. Committee Chairman Ted Cruz (R-Texas) praised Carmel’s qualifications, stating he is “well versed in maritime operations and security,” and is expected to provide strategic advice for federal maritime policy. 

In parallel, President Trump’s nominees for the Federal Maritime Commission (FMC), Robert Harvey and Laura DiBella, outlined their vision to the committee. Harvey, referencing his background in securities litigation and financial regulation, emphasized, “Nothing gets an industry member’s attention like an enforcement action.”  

He promised close scrutiny of carrier alliances to root out anti-competitive practices and affirmed his goal to ensure that “FMC maintains a competitive and reliable international ocean transportation system and protects U.S. consumers, exporters and importers from unlawful, unfair and deceptive ocean transportation practices.”  

DiBella pointed to the realities of global carrier consolidation and asserted the FMC’s central role in ensuring American shippers are treated fairly despite these conditions, saying, “The carriers make the market. However, we need to provide some good oversight.” 

Both FMC nominees endorsed the Ocean Shipping Reform Act of 2022, but flagged ongoing concerns with detention and demurrage, calling for the agency to do more to “uncover efficiencies and why cargo is delayed.” Harvey noted the importance of encouraging innovation through regulation, arguing that fair and competitive markets will attract the private capital needed to solve chronic supply chain problems. 

Carmel used his appearance to urge more robust federal support to counter China’s global dominance in shipping, and he called for U.S. ports to adopt advanced technology to boost productivity.  

“We need to be using technology to leverage our labor and allow them to be more productive. We should use tech not to displace jobs, but to enhance them,” Carmel said.  

He warned that U.S. shipbuilding and merchant marine industries are “on a lifeline” and voiced support for the bipartisan SHIPS for America Act, which would foster domestic shipbuilding and expand the U.S.-flag fleet.  

On the need for demand generation, Carmel stated, “For ships in the international trade, we can’t build them at all. We don’t carry our own commerce. We need demand generation.” 

The Senate Commerce Committee, under Chairman Cruz, has yet to schedule a confirmation vote, with additional hearings expected on maritime policy priorities, including shipbuilding, workforce development, and initiatives such as the Martial Action Plan. Bipartisan leaders like Senator Dan Sullivan (R-Alaska) emphasized that U.S. shipyard capacity and workforce resiliency are essential to offset international competition, particularly from China, and to protect U.S. strategic and economic interests in regions such as the Arctic. 

For more information about the nominee hearings, read this article from Journal of Commerce.